Europe Emerges As Global Leader In Solar Inverter Production
The landscape of photovoltaic inverter manufacturing is undergoing a significant geographic transformation as Western markets pivot toward regional production. While China held nearly 85% of global manufacturing capacity in 2024, Europe has emerged as a major hub for domestic production. Driven by the EU’s Net-Zero Industry Act and concerns over supply chain resilience and cybersecurity, Europe has reached over 100GWac of manufacturing capacity. Unlike the solar module sector, which remains heavily reliant on Chinese-owned facilities, European-headquartered companies now control over 90% of the continent’s inverter production, positioning them to navigate global market fluctuations with greater stability.
The European Union’s regulatory framework has been instrumental in this shift. The Net-Zero Industry Act, adopted in March 2024, mandates that 40% of the EU’s annual net-zero technology needs be met by domestic manufacturing by 2030. This policy provides the long-term certainty required for companies to invest in large-scale facilities. Furthermore, the European Investment Bank introduced financing restrictions in May 2026 that limit access to preferential funding for projects utilizing equipment from high-risk countries, while simultaneously excluding projects using Chinese inverters from EU subsidies.
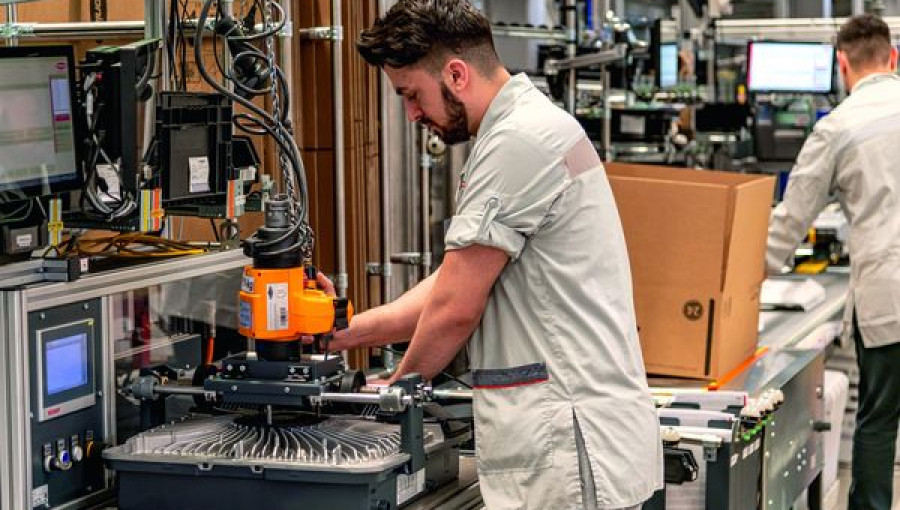
This industrial strategy has fostered a robust domestic base. Germany’s SMA Solar leads with a 40GW facility, followed by Spain’s Power Electronics with a 25GW plant. Together, these firms and others have established Europe as a global leader in inverter production, outpacing the United States and India. This growth is rooted in established engineering expertise and deep customer relationships, rather than a mere relocation of existing Chinese supply chains.
While Chinese manufacturers like Huawei and Sungrow continue to dominate global sales, their manufacturing footprint in Europe remains limited. Huawei has maintained a 3GW facility in the Netherlands for over a decade without expansion, and Sungrow’s new 20GW facility in Poland—expected to be operational in 2027—will only bring the Chinese-headquartered share of European production to roughly 20%. This ensures that the vast majority of regional capacity remains under European control.
Ultimately, Europe’s approach serves as a distinct model for industrial policy. By prioritizing supply chain resilience, cybersecurity, and local job creation, the region has successfully reclaimed a critical segment of the renewable energy market. As the global inverter industry faces a period of cooling demand, European manufacturers are well-positioned to maintain their market share, offering a potential template for other regions and technologies looking to balance climate goals with geopolitical and industrial security.